Earlier growth
Eligible gains accrued before 1 July 2027 retain the existing treatment, including the 50% CGT discount where available.
 0410 439 995 ↗
1 JULY 2027 · CGT PROPERTY VALUATIONS
A new CGT era is coming. Establish your property's market value at the transition date, with an independent valuation your accountant can work from.
Sydney & selected NSW regions · Residential & commercial
ONE DATE. A LASTING REFERENCE POINT.
1 July 2027
New CGT arrangements begin.
Transition valuation: end of 30 June 2027.
WHY THE DATE MATTERS
For affected assets held across the transition, the value at that point separates earlier gains from later gains. A reliable assessment can make a material difference to the calculation.
Eligible gains accrued before 1 July 2027 retain the existing treatment, including the 50% CGT discount where available.
The transition rules use this market value to separate the two periods. Confirm the precise instructed date with your tax adviser.
The new regime introduces cost-base indexation and a minimum 30% tax on relevant real gains. Exemptions and special rules can change the outcome.
Sources: Treasury reform overview · Treasury transition-method explanatory material (draft).
The first reform bill passed Parliament in June 2026. Additional implementation material, including the apportionment method discussed here, was released for consultation in August. Check the final rules with your tax adviser before relying on an election or calculation. Legislation update ↗
EXPLORE THE NUMBERS
A higher substantiated transition value can allocate more growth to the earlier period. Try the simplified comparison below. A valuation must reflect the evidence; it cannot be selected to achieve a tax result.
ILLUSTRATIVE TAX DIFFERENCE
Lower illustrative tax using transition value B.
| Calculation | Value A | Value B |
|---|---|---|
| Earlier nominal gain | $400,000 | $600,000 |
| Tax after 50% discount | $94,000 | $141,000 |
| Indexed transition cost base | $1,100,000 | $1,320,000 |
| Later real gain | $500,000 | $280,000 |
| Tax on later gain | $235,000 | $131,600 |
| Total illustrative tax | $329,000 | $272,600 |
This is a sensitivity illustration for an Australian resident individual with an eligible established investment property held for at least 12 months. It assumes the entire gain is taxed at 47%, a 50% discount on the earlier gain, and the same illustrative CPI factor for both transition values. The 30% minimum does not bind at the assumed rate.
Earlier tax = (transition value − original cost base) × 50% × 47%. Later tax = (sale proceeds − indexed transition value) × 47%. The earlier gain is still included: it is not wiped out by the transition.
It excludes additional costs, improvements, losses, exemptions, ownership shares, progressive tax brackets and other income. Only non-negative gains are modelled. Actual indexation uses the applicable published CPI and legislative rules; the slider is not a CPI forecast. Your accountant must calculate your actual liability and compare any available methods. No tax saving or valuation outcome is promised.
A SECOND PERSPECTIVE
In the default example, the same $1 million nominal gain is divided differently. A higher supported transition value moves $200,000 into the earlier period.
THE SHORT VERSION
Two short animated explainers walk through the transition and the numbers. All figures are illustrative, with the assumptions shown above.
Enable JavaScript to play the animation, or read the transcript below.
From 1 July 2027, affected assets enter a new CGT regime. The transition value separates growth into two periods. Eligible earlier gains retain the existing treatment, including the 50% discount where available. Later gains move to indexation and the new regime. The transition value is market value at the end of 30 June 2027. Register your interest now; a future-date market valuation cannot be finalised today. Confirm eligibility and timing with your accountant.
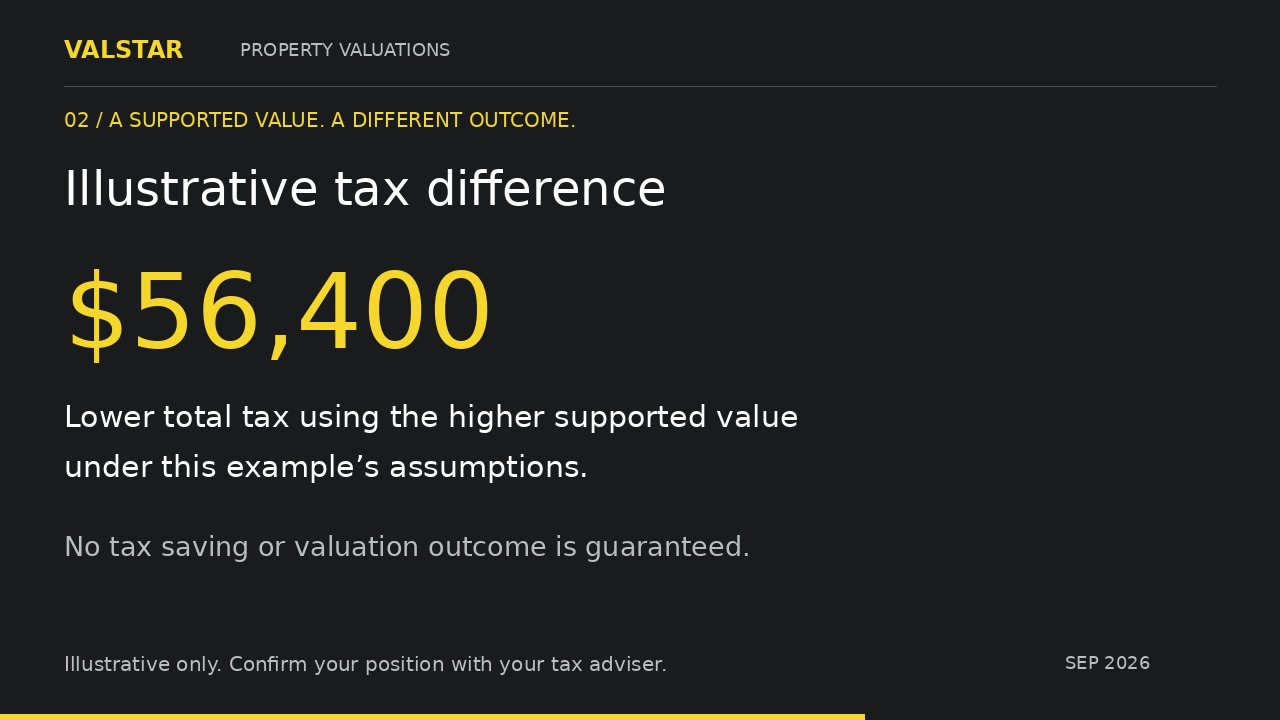
Enable JavaScript to play the animation, or read the transcript below.
Imagine an original cost base of $600,000 and a later sale for $1.6 million. Compare hypothetical transition values of $1 million and $1.2 million. With 10% cumulative indexation, a 50% discount on the earlier gain and a constant 47% tax rate, total illustrative tax is $329,000 using value A and $272,600 using value B. The difference is $56,400. Both earlier and later gains are included. These values are sensitivity inputs, not a choice of valuations. Market evidence must support the assessed value. Other costs, losses, exemptions and tax brackets are excluded. Ask your accountant to calculate your actual position.
AI-assisted animated explainers · On-screen text, no audio narration · Prepared 5 September 2026.
PERSONAL SERVICE. CLEAR EVIDENCE.
Valstar Valuations is an independent property valuation practice. We assess market value, explain the supporting evidence and give you and your adviser a clear report to work from.
Meet Valstar on our main website ↗Send the address, property type and your accountant's requirements. We will confirm whether we can assist, the fee and the next steps.
Keep floor plans, photographs, leases and improvement records. We will discuss inspection timing and information needed for the instructed date.
Once the relevant date and evidence are available, we prepare the valuation. Your tax adviser decides the treatment and any available elections.
BEFORE YOU ENQUIRE
No. The benefit depends on the asset, ownership, exemptions and available calculation methods. A fully exempt main residence generally has no CGT liability. New builds and other special cases may have different treatment. Companies and superannuation funds do not simply follow the individual example on this page. Ask your tax adviser whether the transition affects you.
You can enquire and plan now. A market valuation at a future date cannot be finalised using today's evidence. We will discuss the instructed valuation date, inspection arrangements and reporting when relevant market evidence is available. An enquiry does not reserve an inspection slot or create an engagement.
The valuation date, inspection date and report date can be different. A retrospective assessment may be possible if sufficient evidence is available. Keep records of the property's condition and improvements, and confirm the required effective date with your adviser. There is no blanket requirement stated here to have a completed report before 1 July 2027.
The Treasury draft provides an alternative that estimates transition value using compound growth across the holding period. Actual property growth may have followed a different path. A market valuation can give your accountant evidence to compare methods; it will not necessarily produce a better tax result. The final instrument and eligibility rules need to be checked.
We assess market value independently from relevant evidence. A higher supported transition value can reduce tax in the example above, but we cannot target an inflated figure, guarantee savings or promise ATO acceptance.
The fee depends on the property, effective date, inspection and research required. Send the address and scope, and we will confirm a quotation and expected timing before you decide to proceed.
LET'S TALK ABOUT YOUR PROPERTY
Tell Eddy what you need. Start with the address and any instructions from your accountant, and we can take it from there.
0410 439 995eddy.ceo.valstar@gmail.comContinue to Valstar Valuations to contact us through our main website.
Open Valstar's booking page ↗READ THE ORIGINAL GUIDANCE